Basel Committee Signals a Global Shift in Crypto Capital Rules
The debate over prudential treatment is moving from whether banks should touch digital assets toward how capital rules should distinguish between different forms of crypto exposure.
The institutional debate around digital assets has often focused on demand.
Do banks want to hold crypto assets? Do clients want tokenized products? Are stablecoins useful for settlement? Is there sufficient institutional interest in digital asset infrastructure?
Those questions matter, but they are incomplete.
A bank can see commercial demand and still decide that an activity is unattractive if the prudential treatment makes the balance sheet economics unworkable.
That is why the Basel Committee’s approach to crypto exposures matters far beyond regulatory compliance.
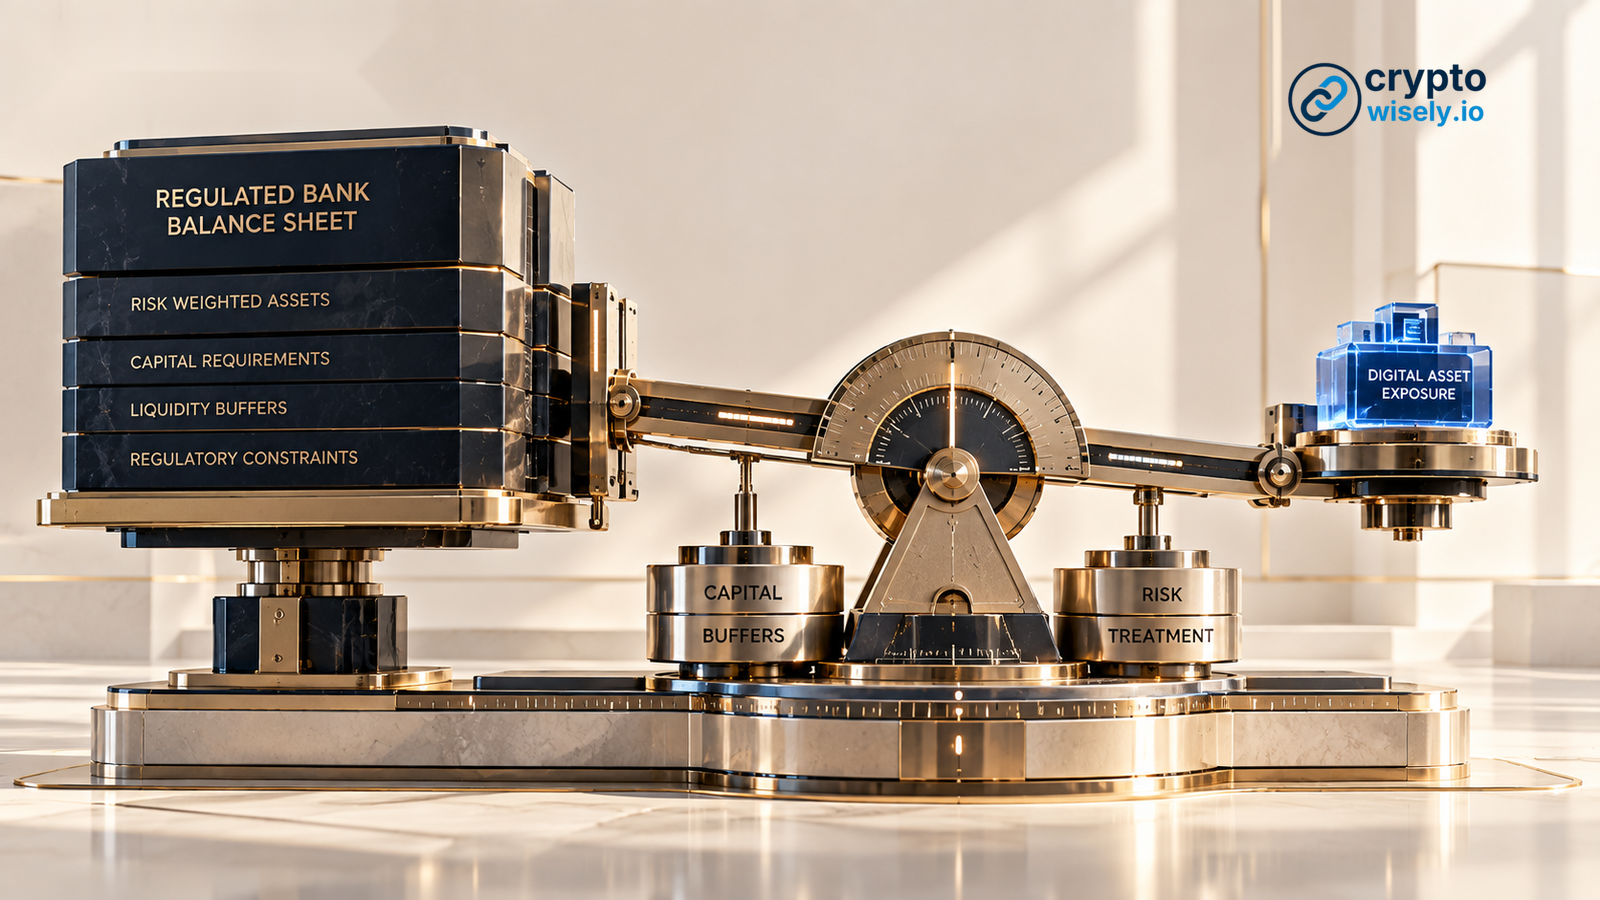
Capital rules shape which activities banks can scale.
Prudential treatment determines economic viability
Bank capital rules are designed to make institutions absorb losses without destabilizing the wider financial system.
The principle is straightforward.
The more risk an exposure creates, the more capital a bank may be required to hold against it.
The difficult part is classification.
Digital assets are not one homogeneous risk category. Bitcoin, tokenized deposits, regulated stablecoins, tokenized securities and other crypto assets can have very different structures, liquidity profiles, legal claims and operational characteristics.
A prudential framework that treats these instruments too similarly can create distortions.
The bank may face a capital requirement that reflects the label attached to the technology rather than the economic characteristics of the exposure.
That can discourage activity even where the underlying use case is relatively controlled.
The original Basel approach was intentionally conservative
The Basel Committee developed a strict framework because digital asset markets introduced several risks that were difficult to fit into conventional banking categories.
Price volatility was one concern.
Legal certainty, market liquidity, custody risk, technology risk and operational dependence on new infrastructure were others.
The conservative treatment was understandable in an early market.
Banks should not receive favorable capital treatment simply because an asset is technologically new or commercially attractive.
But prudential rules also need to evolve when the underlying market evolves.
A framework designed for speculative crypto exposure may not map cleanly onto a tokenized security backed by established legal rights, a stablecoin operating under a regulated reserve model or a blockchain based representation of a conventional financial asset.
The more diverse the market becomes, the more important risk differentiation becomes.
National implementation can fragment the global standard
Basel standards matter partly because they create a common prudential language across jurisdictions.
Banks operate internationally. Capital rules that diverge materially between major markets can change where activities are booked, which products are offered and how groups allocate balance sheet capacity.
In 2025, the debate became more visible as major jurisdictions questioned whether the strictest elements of the global crypto framework should be implemented without modification.
That matters because a global standard is most powerful when large banking systems apply it in broadly comparable ways.
If the United States, United Kingdom, European Union and other major markets develop materially different treatments, digital asset banking activity may become shaped by regulatory geography as much as by customer demand.
This creates another form of market structure.
Capital rules become part of competitive positioning.
Tokenization makes broad classifications harder to defend
Tokenization is one reason the debate is becoming more complex.
A tokenized asset can represent an economic claim that already exists in traditional finance.
The underlying credit risk may be familiar. The legal issuer may be regulated. The asset may sit inside established custody and investor protection frameworks.
What changes is the representation, transfer and settlement architecture.
If prudential treatment focuses too heavily on the use of distributed ledger technology, banks may face a higher capital burden for an asset whose economic exposure is otherwise conventional.
That could slow the adoption of tokenized securities even when the technology improves settlement or collateral mobility.
The same issue appears in different form with stablecoins.
A well governed reserve backed instrument used for settlement is not identical to an unbacked speculative token. The prudential framework needs enough granularity to recognize those differences without creating loopholes.
Capital treatment can shape infrastructure choices
Banks do not evaluate digital asset products only through revenue forecasts.
They evaluate return on capital.
A service can attract customer demand and still fail internally if the capital required to support it reduces the economic return below the institution’s threshold.
This affects product design.
A bank may prefer off balance sheet exposure rather than holding an asset directly. It may use partnerships rather than principal positions. It may provide custody without taking market risk. It may support tokenized settlement while avoiding certain balance sheet exposures.
The architecture of the service can therefore be influenced by prudential treatment.
Regulation does not sit outside the product.
It helps determine the product.
A more risk sensitive model would not mean lighter regulation
Reconsidering strict crypto capital rules should not be understood as an argument for removing prudential discipline.
The relevant question is whether the framework can become more risk sensitive.
Different exposures should attract treatment that reflects their actual structure, liquidity, legal certainty, counterparty risk and operational controls.
That can still produce demanding requirements.
The objective is not to make digital assets easy for banks to hold.
It is to avoid making technologically distinct but economically different instruments collapse into one undifferentiated category.
A mature prudential framework should be conservative where risk is genuinely high and proportionate where the risk is better understood and controlled.
Global alignment will remain difficult
The institutional market is developing faster than international rulemaking normally moves.
Jurisdictions have different policy objectives, banking structures and levels of digital asset adoption. Some want to encourage tokenization and regulated digital money. Others remain more cautious about direct bank exposure to crypto assets.
This makes perfect global alignment unlikely.
But broad consistency still matters.
Banks need to know that similar activities will not produce radically different capital outcomes across major financial centers. Infrastructure providers need to understand the prudential constraints of their banking partners. Tokenization projects need a realistic view of how assets will be treated once they enter regulated balance sheets.
The capital framework becomes part of adoption planning.
The institutional crypto question is becoming more precise
The debate is no longer simply whether banks should be permitted to engage with digital assets.
Banks already interact with the sector through custody, payments, tokenization, settlement, investment products and client demand.
The more useful question is how different forms of exposure should be priced through the prudential framework.
That is a more difficult question.
It is also a sign of market maturation.
When regulators begin distinguishing between forms of digital asset risk rather than treating the entire category as exceptional, the conversation moves closer to ordinary financial regulation.
Institutional adoption will still depend on demand, technology and legal clarity.
It will also depend on whether capital rules reflect the market that now exists rather than the market regulators first encountered.