From Hype to Habit: How Crypto Grew From Speculation Into Infrastructure
A decade of crypto marketing, trust, institutionalization and utility, from the early chaos of 2016 to the infrastructure era of 2026.
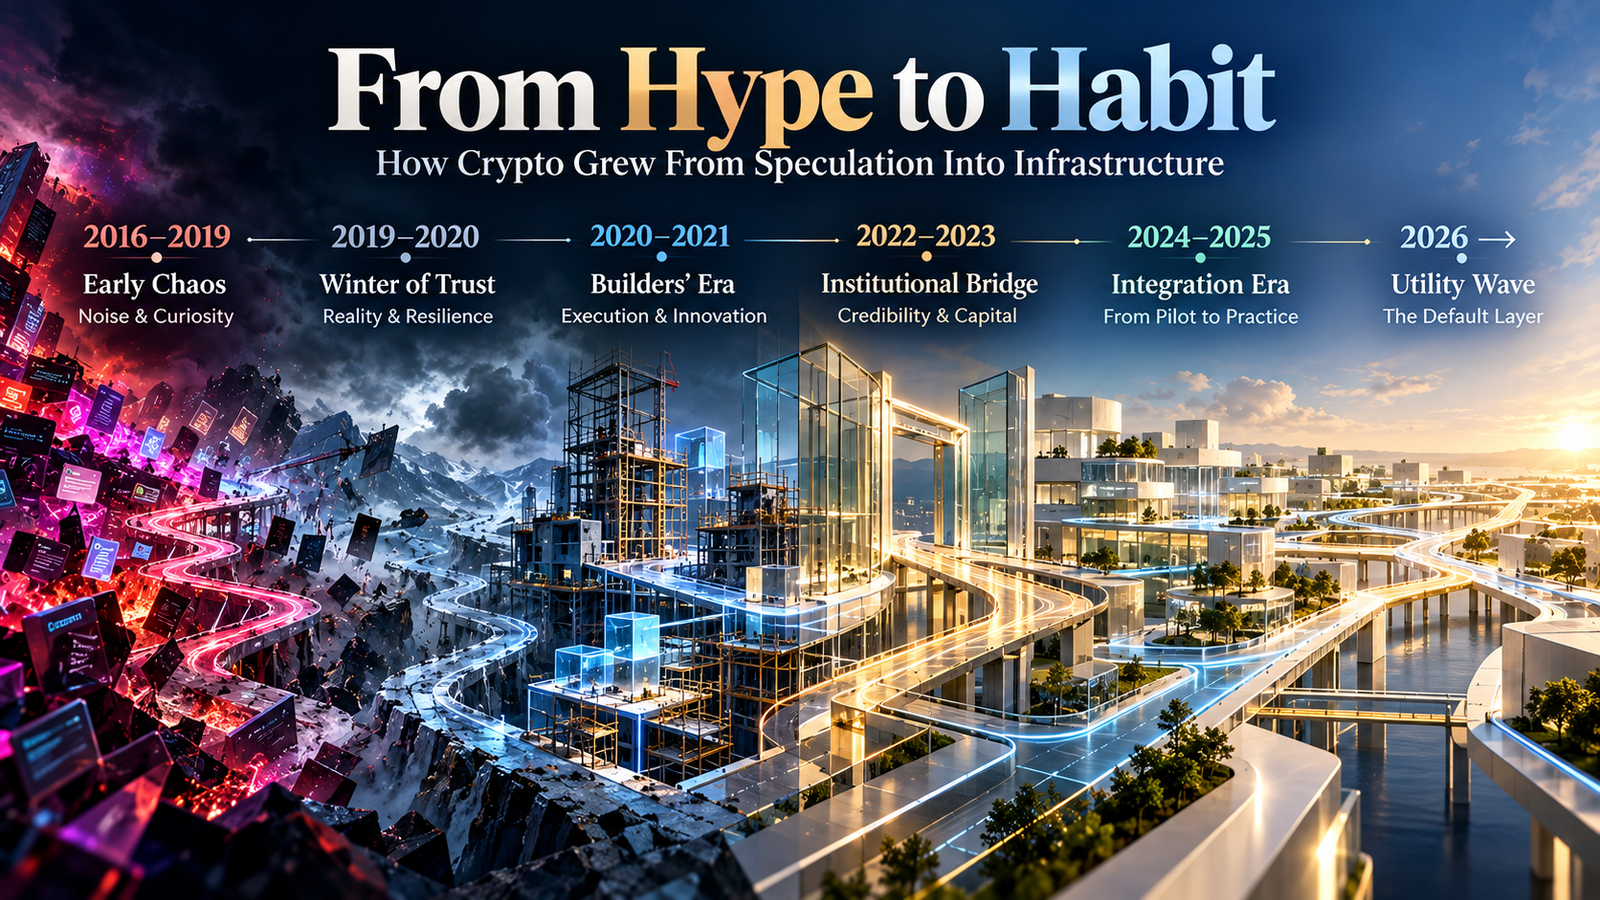
Crypto did not mature in a straight line.
It moved through several distinct phases, each with its own language, incentives and idea of what success looked like.
The early market rewarded attention. The downturn rewarded credibility. The builders rewarded execution. Institutional adoption rewarded control. Integration rewarded utility. The current phase is beginning to reward something less visible: infrastructure that works well enough that users no longer need to think about the technology underneath it.
That progression is also a story about marketing.
The way crypto described itself changed because the industry itself changed.
From 2016 onward, I watched that transition first from the perspective of a marketer and later from inside digital asset businesses operating across exchanges, stablecoins, market infrastructure and institutional adoption.
The most useful way to understand the last decade is not as a sequence of bull and bear markets.
It is as a movement from hype to habit.
1. The Early Chaos: 2016 to 2019
The first wave of crypto marketing was loud because the category itself was difficult to explain.
Projects were selling an idea of the future before most users understood the underlying technology. New tokens launched quickly. Telegram groups grew overnight. Whitepapers became marketing assets. Community size was often treated as evidence of product demand.
Traditional marketing models did not map cleanly onto this environment.
In established categories, marketers usually begin with a recognizable customer problem, define a value proposition and then optimize distribution.
Early crypto often reversed that sequence.
Attention came first.
The product, customer and even use case could remain fluid while the narrative expanded.
This created extraordinary energy, but it also created weak incentives. Projects learned that ambitious language could attract users and capital before execution had been tested. Terms such as decentralization, disruption and revolution became shorthand for value even when the operating model was incomplete.
The market was learning in public.
Users were trying to understand wallets, exchanges, tokens and blockchain networks at the same time that companies were trying to build them.
That uncertainty made communication difficult, but it also made community unusually important.
People did not simply consume products.
They interpreted the category together.
Forums, Telegram groups, early crypto media and social channels became part education system, part distribution layer and part market signal.
The period created many of the cultural patterns that still exist in digital assets today.
It also created the credibility problem that the next phase would have to solve.
2. The Winter of Trust: 2019 to 2020
By the end of the first hype cycle, attention was no longer enough.
Many projects had overpromised. Roadmaps slipped. Some teams disappeared. Others discovered that raising money and building durable infrastructure were very different capabilities.
The market cooled.
The communication environment changed with it.
Users began asking a more demanding question: who can actually be trusted?
This was an important shift for marketers.
A strong narrative could still create interest, but the narrative now needed evidence behind it.
Product updates mattered. Transparency mattered. Security practices mattered. Governance mattered. Teams that continued shipping through a weak market could demonstrate something that could not be produced through advertising alone.
Consistency became a brand signal.
The strongest companies began to communicate differently.
The language became less theatrical. Education became more valuable. Communities were treated less as vanity metrics and more as long term relationships.
The industry discovered a basic principle that financial services had understood for much longer.
Excitement can create attention.
Trust determines whether the relationship survives.
Crypto winter therefore did more than reduce prices.
It changed the standard of proof.
3. The Builders’ Era: 2020 to 2021
The next phase was defined by execution.
While the wider public was paying less attention, developers and product teams were building the systems that would make later growth possible.
Decentralized finance became one of the clearest examples.
Protocols such as Uniswap, Aave, Compound and Curve demonstrated that blockchain based systems could coordinate liquidity, lending and exchange without relying on the same operating structure as a conventional financial intermediary.
The important shift was not that every experiment succeeded.
Many did not.
The important shift was that working products began to replace theoretical promises.
Audits became more important. Smart contract risk became a discipline. Mechanism design moved from whitepaper language into live market behavior.
Infrastructure expanded as well.
Layer 2 development, oracles, indexing, wallets and interoperability tools began solving problems that had limited the usability of the first generation of applications.
The market conversation slowly moved from which token should be purchased toward which infrastructure should be built on.
Then NFTs brought another audience into the ecosystem.
Artists, creators, game developers and consumer brands began experimenting with digital ownership. The market often focused on speculative prices, but the deeper significance was broader.
Blockchain systems were being used to coordinate identity, ownership, community and digital goods.
Crypto was becoming a product environment rather than only an asset class.
For marketing, the lesson was clear.
When the product begins to work, communication becomes easier.
Execution creates its own narrative.
4. The Institutional Bridge: 2022 to 2023
The next correction was more severe.
Industry failures, enforcement actions and governance breakdowns damaged trust again. The market was forced to confront the difference between technological possibility and institutional reliability.
But this period also accelerated professionalization.
The language of the sector began changing.
Stablecoins were increasingly discussed through reserves, payments and settlement rather than only trading liquidity. Custody became an institutional control question. Tokenization moved closer to capital markets infrastructure. Exchange relationships were evaluated through governance, licensing and operational resilience.
Crypto started learning the grammar of finance.
That mattered because the audience was changing.
Banks, asset managers, payment companies and regulators did not evaluate the sector through the same signals as early retail communities.
They wanted evidence.
Who is responsible? Where are assets held? How is liquidity managed? What happens when a transaction fails? Which regulator supervises the activity? What legal claim does the client have?
These questions changed marketing.
Companies could no longer rely on a message built around disruption.
Institutional audiences wanted clarity, controls and operating credibility.
Some of the strongest digital asset brands began presenting compliance, security and infrastructure as part of the value proposition rather than as back office functions.
The tone matured because the buyer matured.
The institutional bridge was therefore not only a capital story.
It was a translation story.
Crypto had to explain itself in a language that regulated finance could evaluate.
5. The Integration Era: 2024 to 2025
By 2024, the line between crypto and traditional finance had become less useful.
The systems were beginning to overlap.
Stablecoins moved deeper into payments and settlement discussions. Tokenized funds and securities became part of institutional pilots and live products. Banks developed custody and digital asset services. ETFs created familiar access routes to assets that had previously required crypto native infrastructure.
Regulation also became more structured.
Europe’s MiCA framework created a common vocabulary for digital asset service providers and stablecoin issuers. Other jurisdictions developed their own approaches to custody, financial promotions, prudential treatment and market access.
The direction was not uniform, but the category was becoming easier to place inside regulated finance.
This changed the role of marketing again.
The strongest message was no longer that blockchain was revolutionary.
It was that a particular system solved a real financial problem.
Faster settlement. Better collateral mobility. Broader market access. More programmable payments. More efficient reconciliation. Stronger transparency.
Utility became more persuasive than ideology.
The best companies increasingly marketed outcomes rather than crypto itself.
This is what integration looks like.
The technology stops asking to be treated as a separate category and begins competing on whether it improves an existing workflow.
That is a more demanding standard.
It is also a healthier one.
6. The Utility Wave: 2026 and Beyond
The logical end point of this progression is not a world in which every consumer talks about blockchain.
It is a world in which the technology becomes increasingly invisible.
Payments can settle through digital rails without the user thinking about the settlement architecture. Tokenized collateral can move between institutions without becoming a consumer narrative. Compliance systems can monitor onchain activity as part of routine risk operations. Digital identity can interact with shared infrastructure without being marketed as Web3.
The important systems become ordinary.
That is how infrastructure usually succeeds.
People do not celebrate payment messaging standards, database synchronization or clearing protocols every time they use them.
They care that the service works.
Digital assets are moving in the same direction.
This changes marketing one more time.
The industry eventually stops marketing crypto and starts marketing outcomes.
Reliable.
Fast.
Controlled.
Transparent.
Programmable.
Accessible across borders.
The underlying technology remains important to the operator, regulator and infrastructure provider.
It becomes less important to the end user.
That is not a loss of identity.
It is a sign of maturity.
The decade changed what credibility means
Looking across the full period, the most important change is not technological.
It is the market’s standard for credibility.
In 2017, a large community and ambitious roadmap could create legitimacy.
By 2020, teams needed evidence that they could survive and execute.
By 2023, institutional buyers wanted governance, compliance and operational control.
By 2026, the strongest proof is increasingly mundane.
The system works repeatedly.
It integrates with other systems.
It can be governed.
It can survive exceptions.
It creates measurable utility.
This is what happens when a category matures.
Narrative does not disappear.
It becomes accountable to reality.
Marketing followed the same path as the market
Crypto marketing began as a way to create belief in an unfamiliar idea.
Then it became a way to rebuild trust.
Then it became a way to explain products.
Then it became a way to translate digital asset infrastructure into the language of regulated finance.
The next stage is simpler.
Marketing needs to explain why the outcome is better.
That may be the strongest indication that crypto has moved from hype to habit.
The category becomes less visible.
The utility becomes more important.
And the market stops asking whether digital assets belong inside financial infrastructure because, increasingly, parts of that infrastructure are already being rebuilt around them.