The Global Rebuild of Financial Architecture
Banking permissions, capital rules, stablecoin settlement, tokenization, AI payments and financial crime controls are moving at the same time, reshaping how the next institutional market stack will operate.
The most important changes in digital assets are increasingly difficult to understand through individual headlines.
A banking permission changes in one jurisdiction. Capital rules are reconsidered somewhere else. Stablecoin frameworks become clearer. Tokenization pilots move closer to production. Payment standards begin preparing for autonomous agents. Financial crime teams face faster cross chain activity.
Viewed separately, these developments can look unrelated.
Viewed together, they point to a broader rebuild of financial architecture.
The market is not only deciding which digital assets will survive. It is defining how regulated institutions will hold them, settle them, finance them, monitor them and connect them to existing financial systems.
Banks are moving digital assets into the operating layer
Bank participation matters because financial markets scale through regulated balance sheets, payment systems, custody relationships and trusted operating processes.
When banks receive clearer permission to interact with blockchain based assets and infrastructure, digital assets move closer to normal financial operations.
That affects much more than direct crypto exposure.
Banks can support settlement activity, provide custody, connect stablecoins to treasury workflows and participate in tokenized market infrastructure. The blockchain stops being treated only as an external technology experiment and begins to sit inside the operating model.
This shift is gradual because every new capability introduces questions around controls, accountability, capital and risk.
The direction nevertheless matters. Institutional adoption becomes more credible when digital asset activity can be handled through the same governance disciplines applied elsewhere in finance.
Capital treatment determines whether institutional exposure can scale
Narrative does not determine institutional adoption on its own.
Balance sheet economics do.
If capital treatment is punitive, unclear or operationally difficult, even an attractive digital asset opportunity can become uneconomic for a regulated institution. If the rules become workable, the same exposure can move from a special case into a standard portfolio or client service discussion.
This is why global capital frameworks deserve as much attention as product innovation.
The treatment of digital assets under prudential rules influences which activities banks can support, how much exposure they can hold and what kinds of services can be offered economically.
Regulatory design therefore becomes part of market structure.
Europe is using regulation as a credibility filter
Europe’s digital asset framework has moved the market toward clearer licensing, governance and disclosure requirements.
That creates friction, but it also creates a more defined operating perimeter.
Custody requirements become more explicit. Stablecoin issuance is assessed inside clearer legal categories. Tokenization initiatives can be tested through controlled environments. Governance and liability become harder to treat as secondary issues.
The tradeoff is familiar.
Innovation moves quickly while regulatory systems move deliberately. The market has to operate inside the gap between the two.
For serious institutions, however, a more demanding framework can also reduce uncertainty by clarifying what is expected before products reach scale.
The Gulf is competing on operational clarity
The Gulf’s role in digital assets is often described through the language of being friendly to innovation.
That description is incomplete.
The more important competitive advantage is operational clarity.
Global institutions care about licensing pathways, banking relationships, settlement efficiency, cross border connectivity and the ability to build real teams under a defined regulatory framework.
Jurisdictions that can combine those elements create infrastructure, not simply favourable messaging.
This is particularly relevant as stablecoins, tokenization and institutional digital asset services begin to overlap. The winning hubs are likely to be those that allow several parts of the market stack to operate together rather than supporting isolated experiments.
Stablecoins are becoming monetary infrastructure in markets with weak rails
Stablecoins mean different things in different economies.
In mature markets, they may be discussed primarily as payment instruments, settlement assets or digital representations of fiat money.
In countries facing inflation, currency instability or limited banking access, their role can be more fundamental.
They can provide access to a more stable unit of account, create alternative settlement routes and reduce dependence on slow or expensive local payment infrastructure.
That makes stablecoins a macroeconomic and policy question as much as a crypto product question.
The same instrument can therefore operate as market infrastructure, payment technology and a substitute for weak monetary rails depending on the jurisdiction.
AI agents introduce another participant into the payment system
Payments infrastructure is also preparing for a world in which software agents can initiate transactions on behalf of users or organizations.
That sounds like a user experience development, but the deeper implications are operational.
Who authorizes the agent? What credentials prove its authority? How does a merchant verify the instruction? Who is responsible when an automated transaction is wrong or fraudulent?
As agents become participants in payment flows, identity, authentication, liability and dispute management have to evolve with them.
Digital assets and programmable money may become relevant here because they can support machine readable rules and continuous settlement. The more important point is that payment architecture itself is expanding beyond human initiated transactions.
Financial crime controls face a speed problem
Digital financial infrastructure also changes the speed of risk.
Threat actors can move across wallets, networks, fintech accounts and jurisdictions faster than many institutional control processes can update.
The challenge is not always a lack of intelligence.
It is the delay between seeing a threat and changing the operating response.
As finance becomes more connected, compliance teams need controls that can respond across systems rather than treating banking, fintech and crypto as separate environments.
This is another reason market architecture matters. New rails create efficiency, but every additional connection also creates another path through which risk can travel.
The market is in a construction period
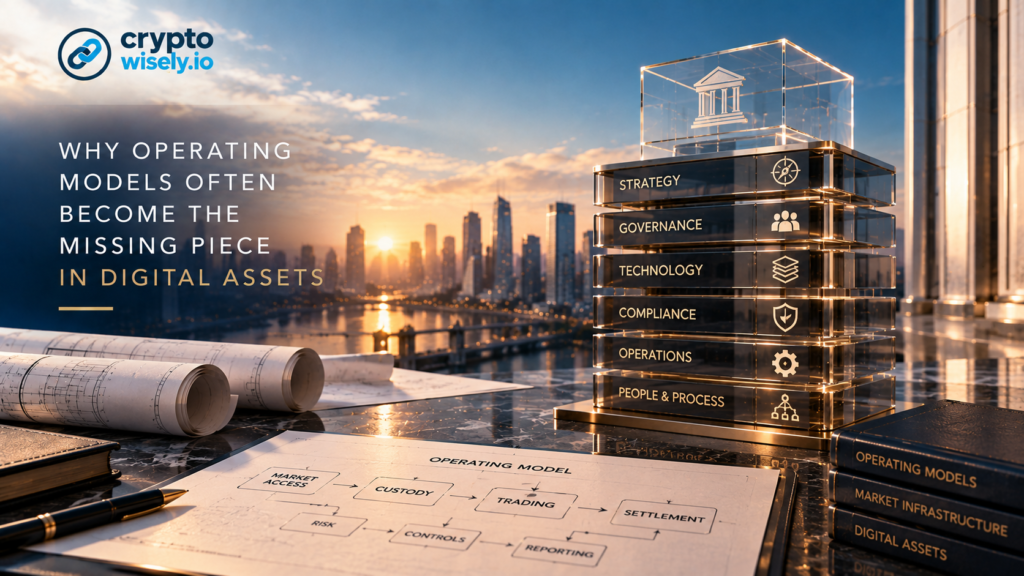
Capital treatment, banking permissions, custody expectations, settlement instruments, tokenization, compliance and automated commerce are all being redesigned in parallel.
Calling this a simple transition understates what is happening.
The financial system is being rebuilt layer by layer while the existing system continues to operate.
That explains why the market can feel fragmented. Different jurisdictions and institutions are updating different parts of the architecture at different speeds.
Over time, those layers are likely to connect more closely.
The important institutional question is therefore not whether digital assets will sit beside traditional finance as a separate system.
It is whether institutions can operate inside a market where custody, settlement, compliance, liquidity, tokenized assets and programmable money increasingly share the same infrastructure.
That is the architecture now being built.