Local Currency Stablecoins Are Becoming an Infrastructure Race
The next phase of stablecoin competition will depend less on issuance alone and more on the banking, conversion, settlement and distribution infrastructure around the asset.
For much of the stablecoin market’s development, one factor dominated the discussion: dollar liquidity.
That was understandable. Most trading depth, exchange activity and crypto settlement demand developed around dollar denominated stablecoins. The dollar became the default settlement language of global digital asset markets.
The next phase is likely to be broader.
Local currency stablecoins are bringing a different set of questions into the market. The focus moves from the token itself toward the infrastructure required to make that token useful inside a domestic or regional financial system.
Issuance is only one component.
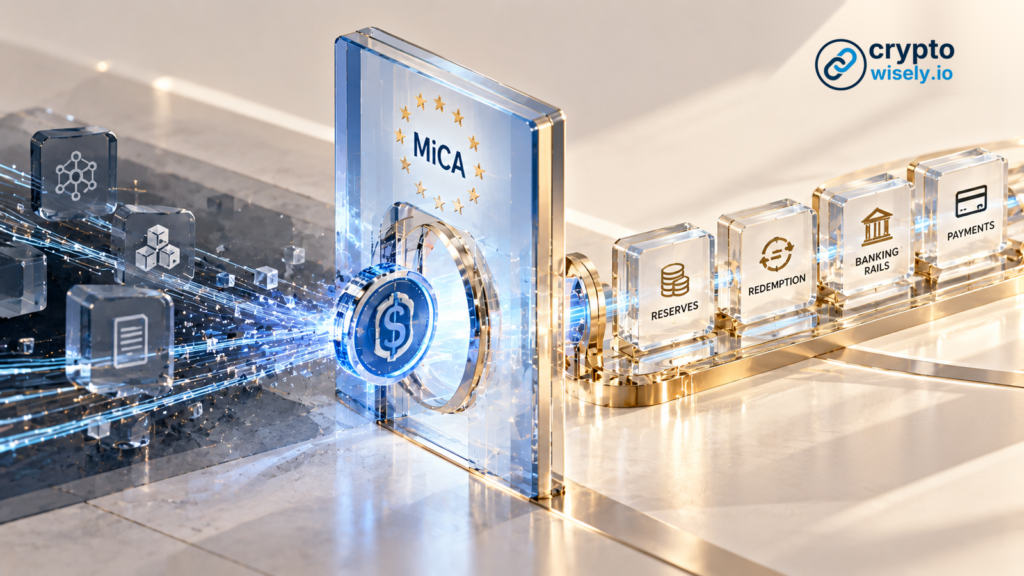
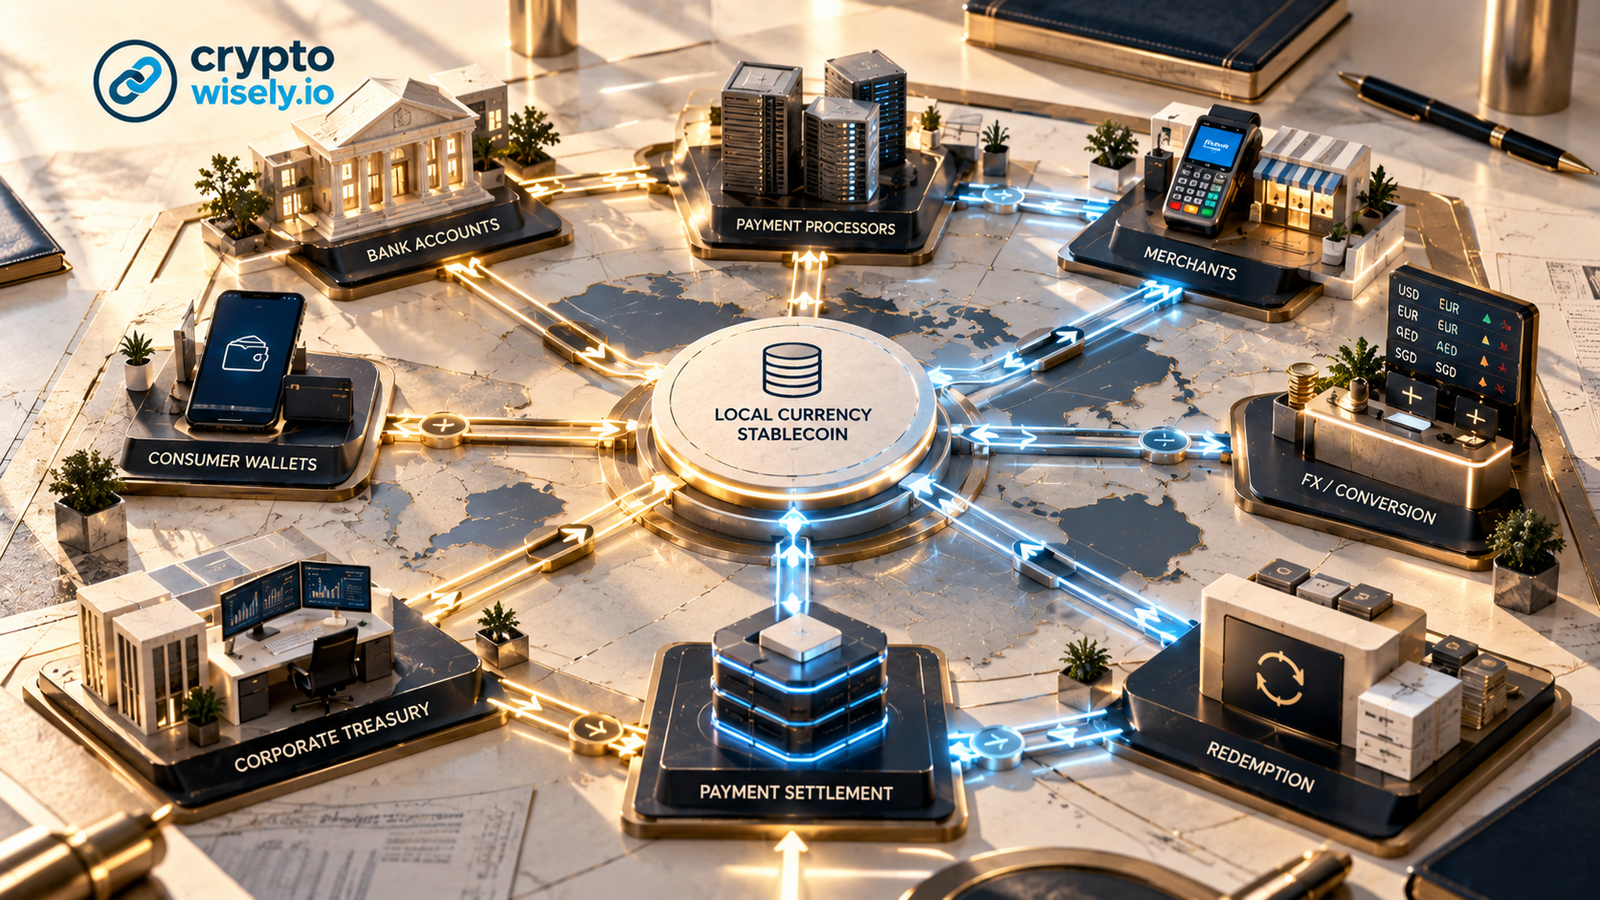
A stablecoin needs banking access, reliable conversion, wallet distribution, settlement capability, compliance controls and credible redemption. Without those layers, the asset can exist technically while remaining commercially isolated.
A local stablecoin needs an operating stack
A local currency stablecoin becomes useful when several systems work together.
The first is issuance and reserves. Users and institutions need confidence that the asset can be redeemed and that the reserve structure is understandable, governed and auditable.
The second is banking connectivity. Stablecoins still interact with bank accounts, payment systems and treasury operations. Banks often remain the point where fiat enters or leaves the system.
The third is wallet access. An asset that cannot be held through the applications people and businesses already use will struggle to reach meaningful scale.
The fourth is conversion. Users need to move between local fiat, major stablecoins and other currencies without unacceptable friction, cost or liquidity risk.
The fifth is settlement. The asset needs a role in real payments, merchant settlement, treasury movement, remittances or institutional transfers.
The sixth is compliance. Identity, transaction monitoring, reporting, governance and auditability must work at the same time as the payment flow.
The strength of the stablecoin depends on the strength of this entire stack.
Distribution may matter as much as issuance
A common mistake is to assume that the issuer naturally owns the market.
That may not be true.
A technically sound stablecoin can still fail to gain adoption if it lacks distribution. A bank, wallet provider, payment application or merchant network may have more influence over usage than the issuer itself.
This creates a different competitive landscape.
The important players are not only stablecoin issuers. They include banks that provide reserve and conversion infrastructure, wallets that provide access, payment companies that connect merchants, liquidity providers that support exchange, and compliance providers that make regulated usage possible.
The asset becomes one component inside a wider service architecture.
Conversion is one of the hardest problems
Local currency stablecoins introduce a practical challenge that dollar stablecoins partially avoided because of the dollar’s existing global liquidity.
A local stablecoin needs efficient conversion in both directions.
Users may want to move from local fiat into the stablecoin. Businesses may need to redeem it into bank money. International users may need to convert between the local asset and dollar based stablecoins. Institutions may need predictable liquidity during large transfers.
If those conversion paths are shallow, expensive or operationally complex, the user experience deteriorates quickly.
This means the success of a local currency stablecoin depends partly on market structure. Liquidity, banking access and redemption are not back office details. They are part of the product.
Settlement turns the token into infrastructure
A stablecoin becomes more interesting when it supports activity that already exists in the economy.
That can include merchant payments, remittances, treasury transfers, business to business settlement or movement between regulated financial institutions.
The technical transfer may be fast, but the surrounding workflow still needs reconciliation, controls and accounting. Businesses need to know when a payment is final. Institutions need to know who is responsible for failed or disputed transfers. Treasury teams need predictable access to liquidity and redemption.
This is where the stablecoin stops being a token story and becomes an operations story.
Regulation shapes the available architecture
Local currency stablecoins sit close to domestic monetary and banking systems. Regulation therefore affects them more directly than many crypto products.
Reserve requirements, issuer eligibility, redemption rules, marketing restrictions and payment regulation can all influence the model.
That does not necessarily reduce innovation. It changes where innovation takes place.
Instead of competing only on token design, providers compete on how effectively they can connect the asset to regulated financial flows.
The infrastructure around the asset may decide the winner
The next stablecoin race is unlikely to be won by issuance alone.
It will be shaped by the operating model surrounding the asset.
Which providers can connect banks, wallets, merchants, fintechs and settlement networks? Which models can make conversion simple enough for users and controlled enough for institutions? Which assets can be redeemed reliably and supported through real payment flows?
Dollar stablecoins established the first large scale model of digital settlement liquidity.
Local currency stablecoins will have to solve a more local and more operational problem.
The strongest projects may not be the loudest issuers. They may be the ones that build the most dependable infrastructure around the asset.