Custody vs. Trading: What Will Banks Actually Offer?
Banks are unlikely to become crypto exchanges. Their institutional role is more likely to begin with custody and expand through regulated exposure, settlement and liquidity partnerships.
A common assumption about institutional digital asset adoption is that regulatory clarity will eventually turn banks into crypto exchanges.
That is unlikely.
Banks and exchanges were built around different operating models. Banks are designed around regulated responsibility, balance sheet management, custody, risk and customer accountability. Exchanges are designed around continuous markets, liquidity, execution and rapid product access.
As the two sectors move closer together, the most likely outcome is not imitation. It is specialization connected through shared infrastructure.
Custody is the natural entry point for banks
Custody fits the institutional logic of banking.
Banks already safeguard assets, maintain records, operate approval hierarchies and manage client assets inside regulated control frameworks. Digital asset custody requires new technology, but the underlying responsibility is familiar.
This makes custody a practical first step.
Institutional clients want digital assets to sit inside processes that legal, compliance, risk and operations teams can understand. They want segregation, reconciliation, reporting and clear accountability.
Banks and regulated custodians can provide that bridge.
Custody alone can enable meaningful digital asset exposure without requiring a bank to operate a twenty four hour trading venue.
Trading is a different business
Digital asset trading requires capabilities that do not naturally sit inside most banks.
Liquidity changes continuously. Markets operate across several venues. Price discovery is fragmented. Activity does not stop at the end of the banking day. New assets and trading pairs can emerge quickly.
Crypto exchanges were built around these conditions.
A bank could reproduce the technology, but technology is only part of the challenge. It would also need the market operations, liquidity relationships and risk culture required to run the business efficiently.
That is why direct competition with exchanges is not the most obvious strategy.
Banks can offer exposure without building an exchange
Banks have several ways to provide digital asset access without reproducing a crypto venue.
They can distribute regulated investment products. They can support tokenized funds or securities. They can provide structured exposure. They can integrate digital asset access into existing wealth or institutional platforms.
These products fit more naturally into established banking controls.
The customer can receive digital asset exposure through a familiar institution while execution and liquidity remain connected to external specialists.
Stablecoins pull banks into settlement
Banks do not need to issue a stablecoin to become important to stablecoin infrastructure.
Redemption, reserves, treasury movement, liquidity and fiat conversion all connect back to banking.
This gives banks a central role even when the digital asset is issued by another organization.
Stablecoins can therefore expand the bank’s role in digital settlement without turning the bank into a consumer facing crypto platform.
The same logic applies to tokenized deposits and other forms of digital bank money. Different instruments can coexist as long as the settlement model is clear and interoperable.
Execution can remain external
A bank may present digital asset trading inside its own interface while relying on exchanges or institutional liquidity providers for execution.
This arrangement reflects the strengths of each side.
The bank manages identity, customer suitability, compliance, risk and the overall relationship. External venues provide liquidity, spreads, market access and execution technology.
The customer sees one product.
The operating model remains modular.
This pattern already exists throughout traditional finance. Banks routinely connect to specialist venues and infrastructure providers while retaining the customer relationship.
Digital assets do not require a completely different principle.
Regulation changes speed more than logic
Different jurisdictions will develop at different speeds.
Some markets will allow banks to offer broader digital asset services quickly. Others will keep custody, execution and distribution more clearly separated. Licensing requirements will affect which partnerships are practical.
These differences matter, but they do not change the underlying logic.
Banks will tend to expand first into activities that fit their existing control model. Exchanges will continue to lead in areas where market depth and execution matter most.
The two will connect where infrastructure makes cooperation efficient.
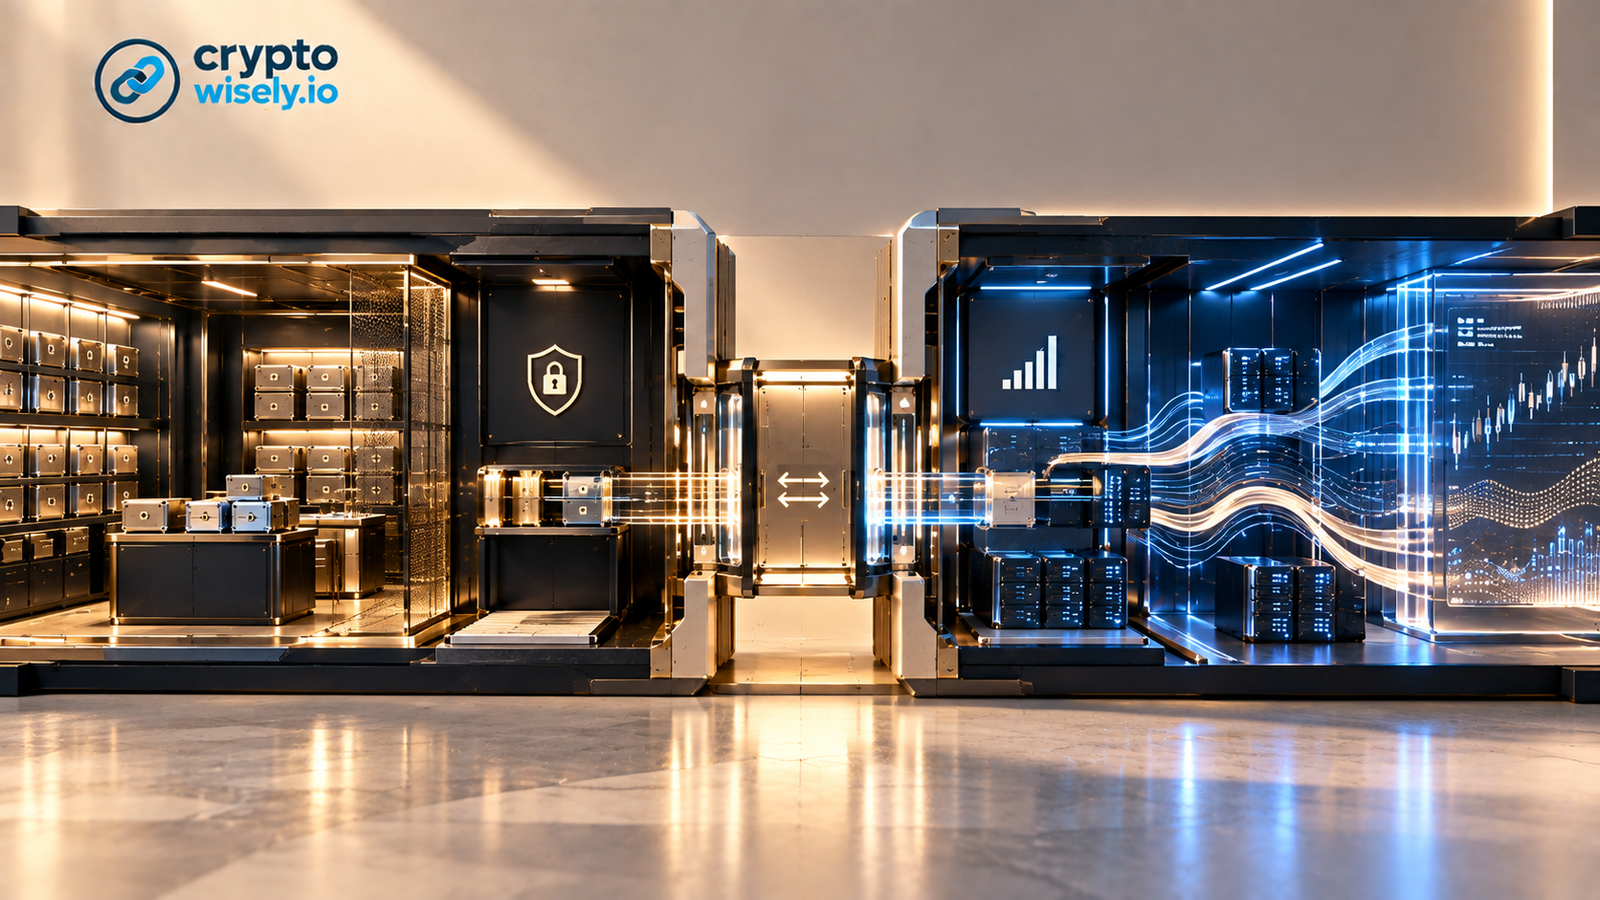
The convergence layer sits between custody and execution
The important market opportunity is therefore not simply custody or trading.
It is the infrastructure that connects them.
Assets need to move safely between custody and execution. Settlement needs to be reliable. Liquidity needs to be accessible without weakening control. Compliance data needs to travel with the customer relationship. Reconciliation needs to work across institutional boundaries.
This middle layer will determine how smoothly banks and exchanges can operate together.
Customers will care less about the boundary
A mature digital asset service may allow a customer to hold assets with a regulated custodian, access liquidity from specialist venues, settle through digital money and see everything inside one interface.
The customer does not need to know which institution performs each function.
What matters is that responsibility remains clear behind the interface.
Banks are unlikely to become crypto exchanges.
They do not need to.
Their more important role may be to provide the custody, trust and regulated access that allow exchange capabilities to become part of institutional finance.