The Dual Ownership Model: Who Owns the Customer in a Layered Financial System?
As banking, digital platforms and regulated market infrastructure converge, customer ownership is giving way to a more distributed model of access, responsibility and control.
For a long time, customer ownership in financial services was relatively easy to describe.
Banks opened the account, controlled the relationship, held the data, managed compliance and provided most of the products. The institution that owned the account largely owned the customer relationship.
Digital platforms changed that structure.
Fintech companies moved the interface away from the bank. Crypto exchanges went further by giving users direct access to markets, assets and transfers outside traditional banking applications.
The customer relationship became distributed before the industry had a clear language for describing what had happened.
Regulation is now making that distribution more visible.
Ownership is no longer one thing
The word ownership can be misleading because several different forms of control sit inside a financial relationship.
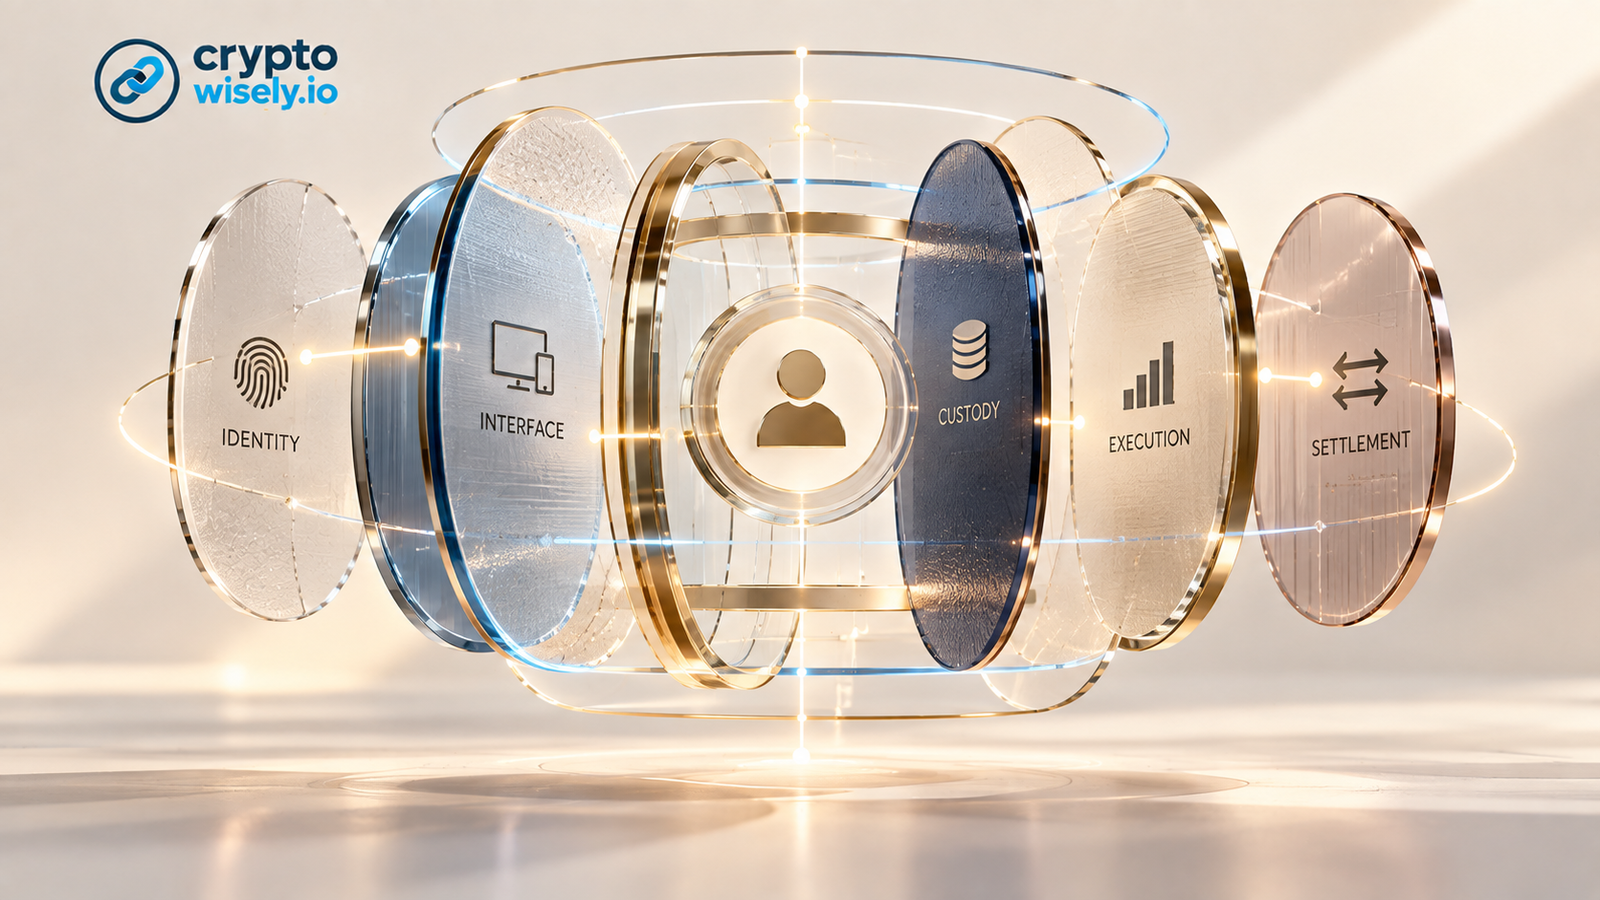
One institution may control identity and regulatory onboarding. Another may control the daily interface. Another may hold the assets. Another may execute transactions. Another may provide the settlement infrastructure.
All of them interact with the same customer, but none necessarily controls the entire relationship.
This is better understood as a layered model.
The customer has one experience while responsibility is distributed underneath it.
Banks retain important control points
Banks remain strong in areas where regulated accountability matters most.
They manage identity, legal accounts, capital, settlement relationships and a large part of the compliance framework. They also carry an institutional trust advantage that is difficult to reproduce quickly.
These control points remain valuable even when the customer spends most of the day inside another application.
A platform may own the interaction. The bank may still own critical parts of the regulated relationship.
This is why the idea that digital platforms simply replace banks is too simple.
The interface can move without the underlying responsibilities moving at the same speed.
Platforms own frequency and context
Digital platforms have a different advantage.
They often know more about what the customer is trying to do at a given moment because they control the interaction layer.
They see navigation, product discovery, transaction intent, engagement and behavior. They can design flows around specific use cases and adapt faster than large financial institutions.
That gives them influence over product choice even when they do not own the balance sheet or regulatory relationship.
In many markets, this interaction layer is commercially more important than the account itself.
The institution that controls the interface can shape what the customer sees, compares and chooses.
Digital assets add another ownership layer
Digital assets make the structure more complex because custody, execution and settlement can be provided by different organizations.
A customer may access a digital asset through a bank interface while the asset is held by a specialist custodian and execution is provided by an exchange. A stablecoin payment may begin inside a fintech application, move through a blockchain network and redeem into a bank account.
The customer experiences one service.
The operating model contains several institutions.
This makes responsibility more important than branding. Customers may not know which provider performs each function, but the system still needs clear accountability.
Regulation distributes responsibility rather than eliminating it
Regulation does not automatically return the customer to one institution.
It tends to define who is responsible for specific activities.
Custody rules define responsibilities around safekeeping. Financial promotion rules define responsibilities around communication. Payment rules define responsibilities around movement of value. Outsourcing rules define responsibilities between institutions and service providers.
The result is not centralized ownership. It is more explicit distribution of responsibility.
This is why future customer relationships may be better understood through control points rather than logos.
Who controls identity? Who controls data? Who controls the interface? Who controls the assets? Who controls execution? Who is accountable when something fails?
Those questions reveal the real structure.
Data will remain a strategic boundary
Customer data is one of the areas where ownership will continue to be contested.
Banks possess regulated financial history and identity data. Platforms possess behavioral data and product context. Exchanges possess trading and market behavior. Infrastructure providers may hold operational data about settlement and transfers.
The value is not only in possessing data. It is in being permitted to use it and being able to connect it responsibly across services.
As financial systems become more modular, data governance will become part of the customer ownership model.
Trust is also distributed
Customers may trust different institutions for different reasons.
They may trust a bank with safekeeping, a platform with usability, an exchange with execution, and an infrastructure provider without knowing its name at all.
This makes trust increasingly functional.
A single brand does not need to dominate every layer if the overall service feels reliable and responsibility is clear.
The future customer relationship is coordinated
Financial services are becoming layered.
That means customer ownership is becoming coordinated rather than exclusive.
The strongest institutions will understand which parts of the relationship they need to control directly and which parts they can share with partners. They will also make sure that distributed delivery does not create distributed accountability.
The customer may see one experience.
The architecture behind that experience will increasingly belong to several institutions at once.