The Future of Bank and Exchange Infrastructure: What a Hybrid Model Looks Like
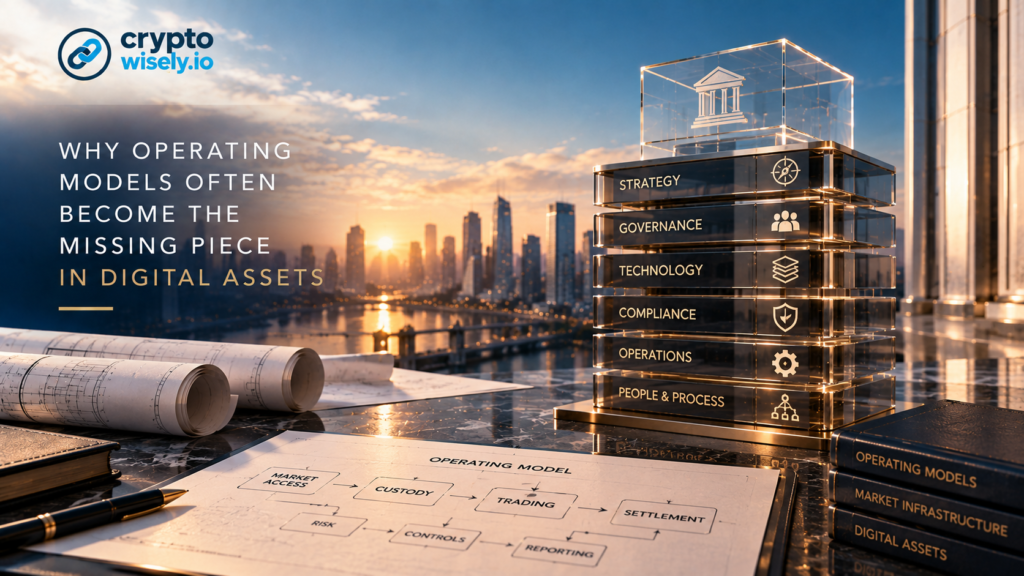
Banks and crypto exchanges are unlikely to replace one another. The more realistic end state is a shared operating model built around custody, compliance, execution, liquidity and settlement.
Banks and crypto exchanges are moving toward the same market infrastructure, but that does not mean they are becoming the same kind of institution.
The more realistic end state is a hybrid operating model.
Banks retain the functions that depend on regulated responsibility, balance sheet strength, custody and customer accountability. Exchanges retain the functions that depend on liquidity, execution quality, product velocity and continuous market access. Infrastructure providers connect the two.
This is less dramatic than the idea of one side replacing the other. It is also more consistent with how financial systems usually evolve.
Custody remains an institutional anchor
Custody is one of the clearest examples.
Banks and regulated custodians are well positioned to provide safekeeping, segregation, governance and accountable control. Exchanges are strong at turning digital assets into usable products and giving users access to markets.
A hybrid model does not require one side to abandon its strength.
Assets can remain inside a controlled custody environment while users access execution and liquidity through connected venues. The customer does not need to choose between institutional protection and efficient market access if the infrastructure can connect the two safely.
That requires strong controls around asset movement, authorization and reconciliation. It also requires clear responsibility when assets cross organizational boundaries.
Identity can become a shared foundation
Banks have deep experience with customer identity, compliance and legal responsibility. Exchanges have built highly digital onboarding and engagement flows.
A mature model can combine these capabilities.
One regulated identity layer can support access to several products and execution environments. The user sees a coherent experience while the infrastructure underneath maintains the required controls.
This is important because compliance does not need to dominate the user experience in order to remain effective. Good architecture can keep the control layer active without forcing the customer to navigate a separate process for every service.
Settlement becomes configurable infrastructure
Digital asset markets introduced the expectation that value can move continuously. Traditional finance introduced the expectation that settlement must be controlled, legally clear and operationally recoverable.
A hybrid model needs both.
Speed can vary by transaction type, counterparty and risk. Finality can be immediate in some workflows and more controlled in others. Intervention points may exist where the operating model requires them. Reconciliation can remain visible even when the movement of value becomes faster.
Settlement should therefore be treated as a risk design decision, not as an ideological argument about whether every transaction should be instant.
Stablecoins and tokenized bank money extend the model
Stablecoins are increasingly relevant because they create a digital settlement asset that can operate outside traditional banking hours.
That does not remove banks from the architecture.
Banks can provide reserve services, liquidity, redemption, treasury connectivity and institutional control. Stablecoin providers can provide programmable movement and distribution. Exchanges can provide liquidity and conversion.
Tokenized deposits and other forms of digital bank money can sit alongside these instruments rather than automatically replacing them.
The important question is which instrument works best for a given workflow and how reliably it connects to the rest of the system.
Tokenized assets remain connected to legal infrastructure
Tokenized securities create another hybrid layer.
The blockchain can improve synchronization, transfer and settlement while legal ownership, investor protection and enforcement remain connected to regulated frameworks.
That means tokenization works best when legal structure, custody and settlement are designed together.
The chain can improve the record and movement of the asset. It does not remove the institutions responsible for defining ownership and protecting investors.
Execution remains an exchange strength
Crypto exchanges have developed capabilities that are difficult for banks to reproduce quickly.
They manage continuous markets, fragmented liquidity, rapid price discovery and a wide range of digital asset pairs. Their technology and operating culture are built around execution.
Banks may offer digital asset trading inside their own interfaces without internalizing every execution function. Liquidity can be sourced externally while the bank manages the customer relationship, compliance and risk framework.
The customer may see one product. The execution architecture can remain distributed.
The user experience will hide the architecture
The most mature version of this model may appear very simple from the outside.
One application can show cash, digital assets and tokenized products. One identity can support several services. One portfolio view can hide the fact that different institutions are providing custody, liquidity, settlement and compliance.
The underlying system can be modular even when the customer experience is unified.
That is likely to be one of the defining characteristics of the next stage of digital finance.
Convergence is an operating model, not a merger of identities
Banks do not need to become exchanges. Exchanges do not need to become banks.
They need compatible infrastructure and clearly defined responsibilities.
The institutions that succeed will be those that understand where they should retain control, where they should connect to specialists, and how the overall system behaves when something goes wrong.
The future bank and exchange hybrid is therefore not a single institution.
It is a shared operating model.